Key findings
- The available evidence points to a fragile retail environment: official sales and inflation data sit alongside industry reports of sluggish sales, lower footfall and continued pressure to hold shop prices down.
- The key management problem is not simply generating visits or impressions. It is converting cautious intent into profitable transactions without training customers to wait for ever-deeper discounts.
- Lower shop-price inflation can protect demand in the short term, but it can also conceal a margin and cash-flow problem, particularly for independent retailers and smaller chains with less buying power.
- Stores still matter, but weak footfall raises the threshold for physical-space productivity. Locations should be managed as local service, fulfilment and customer-retention assets rather than judged only by till sales.
- The outlook to January depends on whether confidence and real purchasing capacity improve enough to support discretionary volumes. Retailers should use scenario-based trading plans rather than commit to a single ‘Golden Quarter’ assumption.
The thesis: seasonal demand is not the same as a retail recovery
UK retailers should treat the run-in to January 2027 as a conversion and margin-management test, not as evidence that seasonal demand will automatically repair weak trading. That distinction matters because a customer can be willing to browse, compare prices and delay a purchase while remaining unwilling to commit at the price, channel or delivery proposition on offer.
The September evidence presents precisely the kind of mixed backdrop that makes broad extrapolation risky. The Office for National Statistics provides the official read on retail sales and consumer-price inflation, while the British Retail Consortium’s contemporaneous monitors describe sluggish sales, falling footfall and retailers maintaining low prices despite cost pressures. The Bank of England’s Agents’ Summary adds a business-conditions perspective, and its July Monetary Policy Report provides the wider monetary and household-demand context. Taken together, these sources support caution: retail conditions may contain pockets of resilience, but they do not establish a uniform recovery in discretionary spending. ↗ ↗ ↗ ↗ ↗ ↗ ↗
For managers, the implication is practical. A sales plan built on an assumed festive uplift can produce excess seasonal inventory, undisciplined markdowns and avoidable labour costs. A plan built around conversion asks more useful questions: which customer missions remain active; which purchases are being deferred; what evidence of value is credible; and where does fulfilment friction cause a customer to abandon a basket? This is not a pessimistic case. It is a more demanding commercial one: retailers can still capture spend, but they must earn it transaction by transaction.
Why the gap between interest and purchase matters
The central mechanism is caution. When household budgets remain under pressure, shoppers need not withdraw from the market altogether. They may substitute down, purchase later, seek a promotion, spread purchases across pay cycles, favour familiar brands or move between store and digital channels before buying. Those behaviours can preserve some demand while making weekly sales volatile and forecasting difficult.
That helps reconcile a seemingly contradictory set of indicators. Retail-sales data measure realised spending and volumes; footfall measures visits; shop-price monitoring captures retail price movements; and business intelligence captures firms’ reported operating conditions. None is a complete proxy for consumer confidence or for profitability. A rise in visits without a comparable rise in transactions can signal research behaviour rather than recovery. A low-price environment can support unit demand while worsening gross margin. Conversely, a weak month in an official series does not prove that every category, place or retailer is deteriorating. ↗ ↗ ↗ ↗
This is why seasonal trading should be managed through a funnel, not a headline sales forecast. Retailers should monitor qualified traffic, availability of priority lines, basket conversion, units per transaction, fulfilment choice, returns and gross-margin contribution together. A promotion that increases transactions but displaces full-price demand or generates high returns has not necessarily improved the business. Equally, a modest sales gain achieved through fewer, better-qualified visits may be commercially stronger than a larger footfall gain.
The interpretation has limits. September is an early signal for a trading period extending through January, not a verdict on it. Weather, household bills, wage and employment conditions, interest-rate expectations, competitor actions and any clearer fiscal messaging can alter spending decisions quickly. The appropriate response is therefore contingent planning, not a confident point forecast. ↗ ↗ ↗
Value needs to be credible, not merely loud
The BRC-NIQ monitor’s emphasis on retailers keeping prices low despite rising cost pressures identifies the most important trade-off of the period. Price restraint can be a rational demand defence: it protects a retailer’s value proposition and may help households keep purchasing essential or modest discretionary items. But it transfers pressure into the retailer’s economics unless it is offset by lower buying costs, better mix, greater productivity or operational savings. ↗
The strategic error is to interpret this environment as a call for blanket discounting. Repeated, poorly differentiated promotions can make customers defer purchases until the next event, reduce the perceived fairness of regular prices and leave independents unable to match the discounts of larger competitors. For a small high-street retailer, the cash consequence can be especially severe: seasonal stock is paid for before it is sold, while discount-led revenue may fail to cover occupancy, staffing and finance costs.
Sanctuary’s recommendation is to make value a proposition with evidence rather than a volume of promotional messages. That may mean clear good-better-best ranges; a focused entry-price offer; bundles that solve a customer need; loyalty benefits that reward repeat custom rather than indiscriminate discounting; transparent delivery and return terms; or service expertise that lowers the risk of a discretionary purchase. The correct choice varies by category. The shared discipline is to set a commercial purpose for every offer: acquire a customer, clear genuinely ageing stock, protect a key price point, increase attachment or defend a local competitor position. If the offer has no stated purpose and no contribution hurdle, it is likely to become margin leakage.
Retailers should also separate price perception from average discount. A tightly available-value line, consistently in stock and easy to compare, may do more for trust than a headline promotion that excludes popular products or expires before many customers can act. That is a management-capability issue: merchants, marketing teams and store colleagues need one account of what the offer is for and what customers can actually obtain.
Footfall is a warning about store productivity, not a case against stores
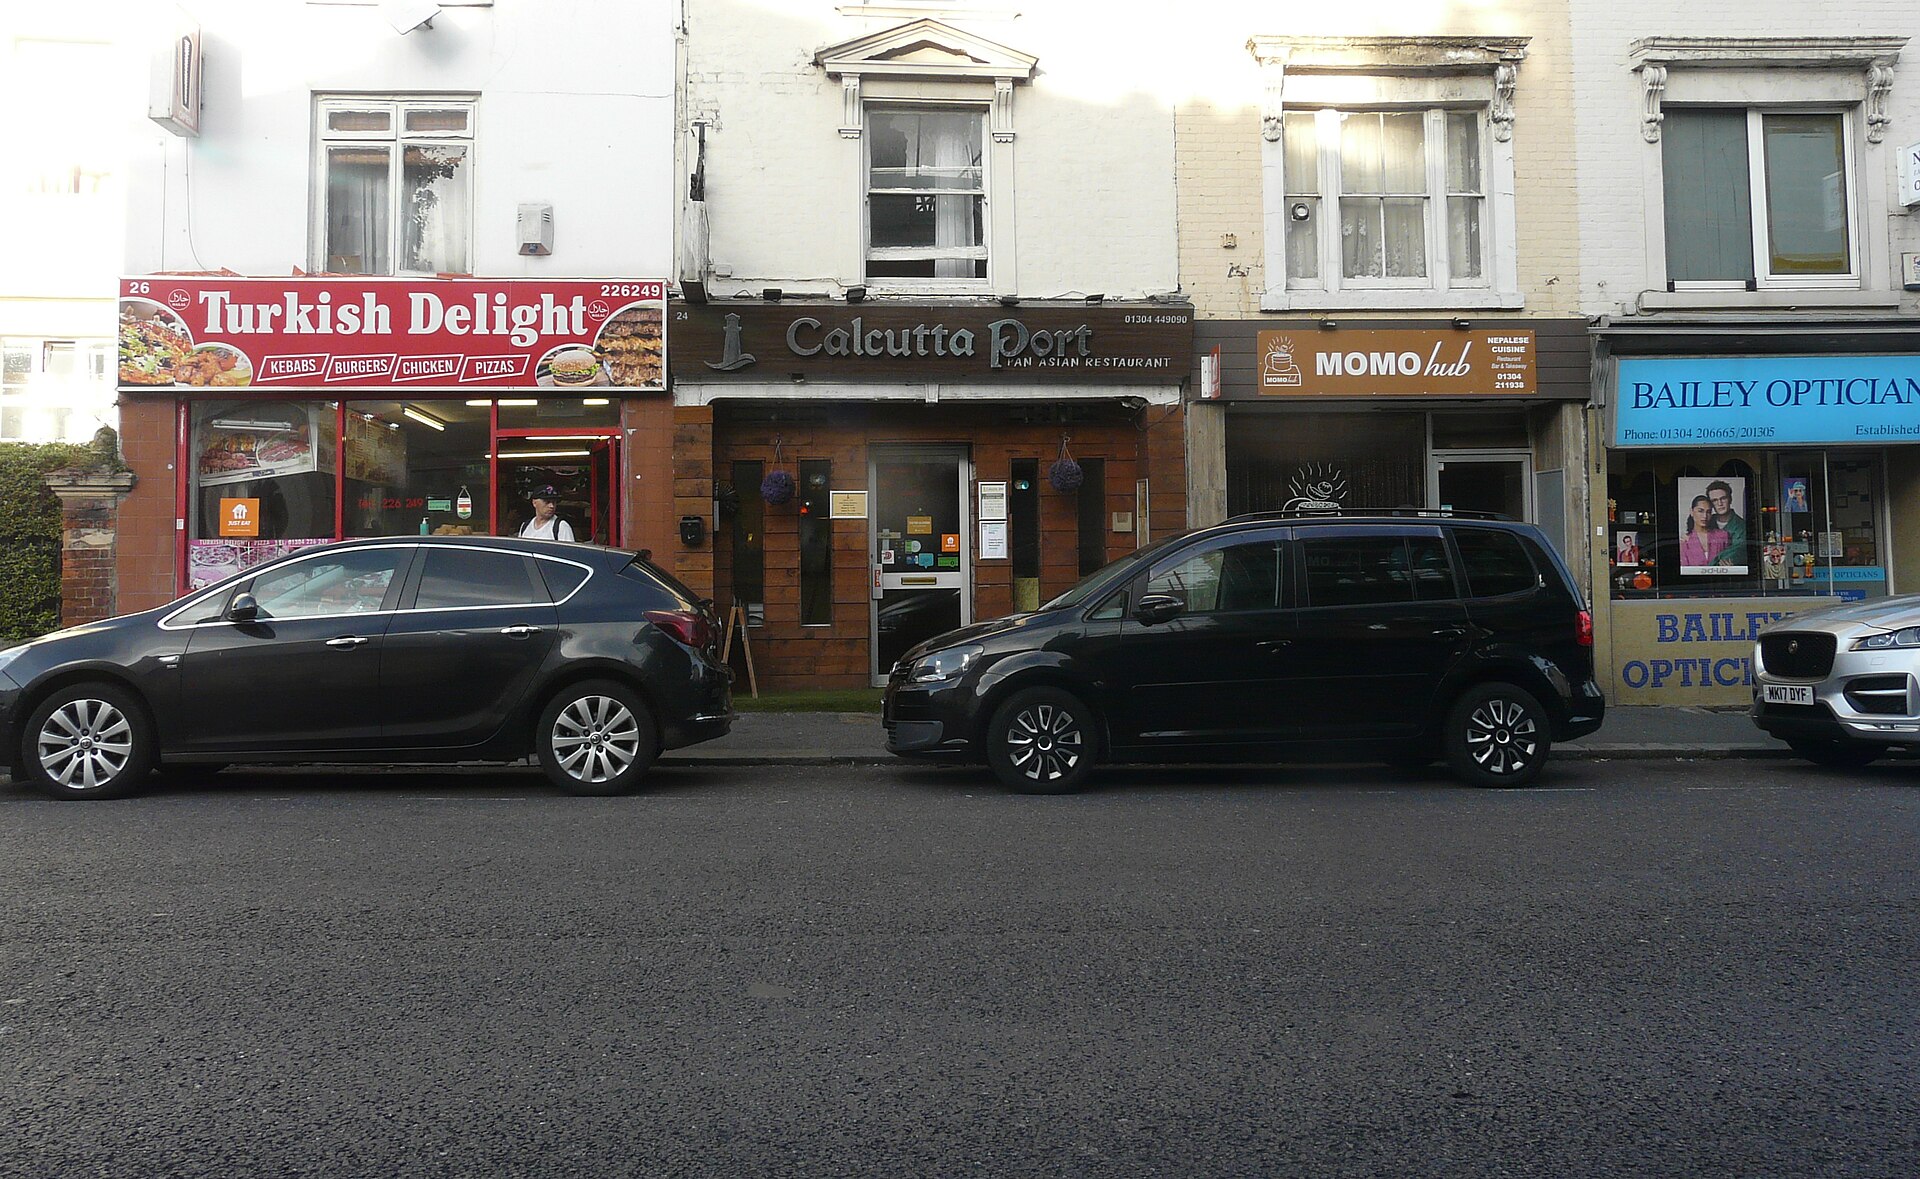
The reported fall in footfall should not be read as proof that physical retail has lost its strategic role. It does, however, make passive store economics harder to defend. If fewer people arrive by default, each location needs a clearer job: local discovery, trusted advice, collection and returns, rapid fulfilment, appointment-led selling, community connection or repeat-customer service. ↗
This matters beyond national chains. High streets are local economic infrastructure, supporting small employers, first management roles, routes into customer-service work and entrepreneurial businesses. Yet the local-value argument does not exempt a business from commercial discipline. A shop that creates footfall for surrounding businesses but consistently loses money cannot sustain those benefits. Local authorities, landlords and business groups therefore have an interest in measures that improve the quality of a visit—safe and accessible streets, practical parking or public transport, coordinated events, wayfinding and digital visibility—rather than simply pursuing an undifferentiated rise in visitor numbers.
For retailers, store reporting should reflect the customer journey. Allocate appropriate credit for orders researched in store, collected there, returned there or generated through local clienteling, while keeping clear control of the labour and fulfilment costs involved. The goal is not to make every store look successful through generous attribution. It is to understand whether the location creates profitable customer value across channels. That is especially important when lower footfall makes single-channel till sales an increasingly incomplete performance measure.
A practical plan for the period to January
A robust trading plan should contain three scenarios. In a cautious case, customers remain highly promotion-aware, footfall stays subdued and discretionary purchases concentrate around clear value events. In a central case, essential and gift-led demand holds up but category performance remains uneven. In an upside case, improving confidence and purchasing capacity produce broader discretionary conversion rather than merely heavier promotional activity. The evidence currently supports planning around the first two cases more strongly than treating the upside as the base case. ↗ ↗ ↗ ↗
The operational priorities follow from that judgement:
• Protect availability on proven, high-intent lines, but stage commitments for speculative seasonal stock where supplier terms allow.
• Set promotion guardrails before peak events: eligible products, inventory limits, expected incremental sales, margin floor and a post-event review of repeat purchasing and returns.
• Give store and customer-service teams authority to resolve the frictions that lose conversions—unclear stock status, delivery uncertainty, exchange complexity and inconsistent price communication.
• Review performance at local level. A national average can conceal very different conditions across town centres, retail parks, cities and catchments.
• Use a weekly exception dashboard rather than relying on topline sales: conversion, full-price mix, markdown rate, stock availability, return rate, labour productivity and cash tied up in inventory should sit together.
The counterargument is that caution can itself become self-defeating. Retailers that cut stock, service and marketing too far may miss demand when it does appear, yielding customers to better-prepared competitors. That is valid. The answer is not retrenchment for its own sake, but reversible commitments: protect the capabilities that remove customer friction, test offers in controlled cohorts or locations, and expand only when conversion and contribution evidence justify it.
The key invalidation signal for the cautious thesis would be a sustained and broad improvement in discretionary purchasing and visits without a corresponding escalation in promotional intensity. Until such evidence emerges, the stronger management stance is to regard every seasonal opportunity as conditional: demand exists, but profitable demand must be designed for and measured carefully. ↗ ↗ ↗ ↗
Research foundation
References
- Office for National Statistics (2026). Retail sales, Great Britain: September 2026. Office for National Statistics statistical bulletin.Source ↗
- British Retail Consortium and KPMG (2026). Sluggish sales as shoppers look for Budget boost. BRC Retail Sales Monitor.Source ↗
- British Retail Consortium and Sensormatic Solutions (2026). Budget must deliver for shoppers as footfall drops. BRC Footfall Monitor.Source ↗
- Office for National Statistics (2026). Consumer price inflation, UK: September 2026. Office for National Statistics statistical bulletin.Source ↗
- British Retail Consortium and NIQ (2026). Retailers keep prices low despite rising cost pressures. BRC-NIQ Shop Price Monitor.Source ↗
- Bank of England (2026). Agents' summary of business conditions: September 2026. Bank of England Agents' Summary.Source ↗
- Bank of England Monetary Policy Committee (2026). Monetary Policy Report: July 2026. Bank of England.Source ↗
- John Baker. Hero image: Retail outlets, High Street - geograph.org.uk - 7644448.jpg. Wikimedia Commons · CC BY-SA 2.0.Image source ↗
Related Sanctuary capabilities
From analysis to implementation.
Discussion
No approved comments yet.